
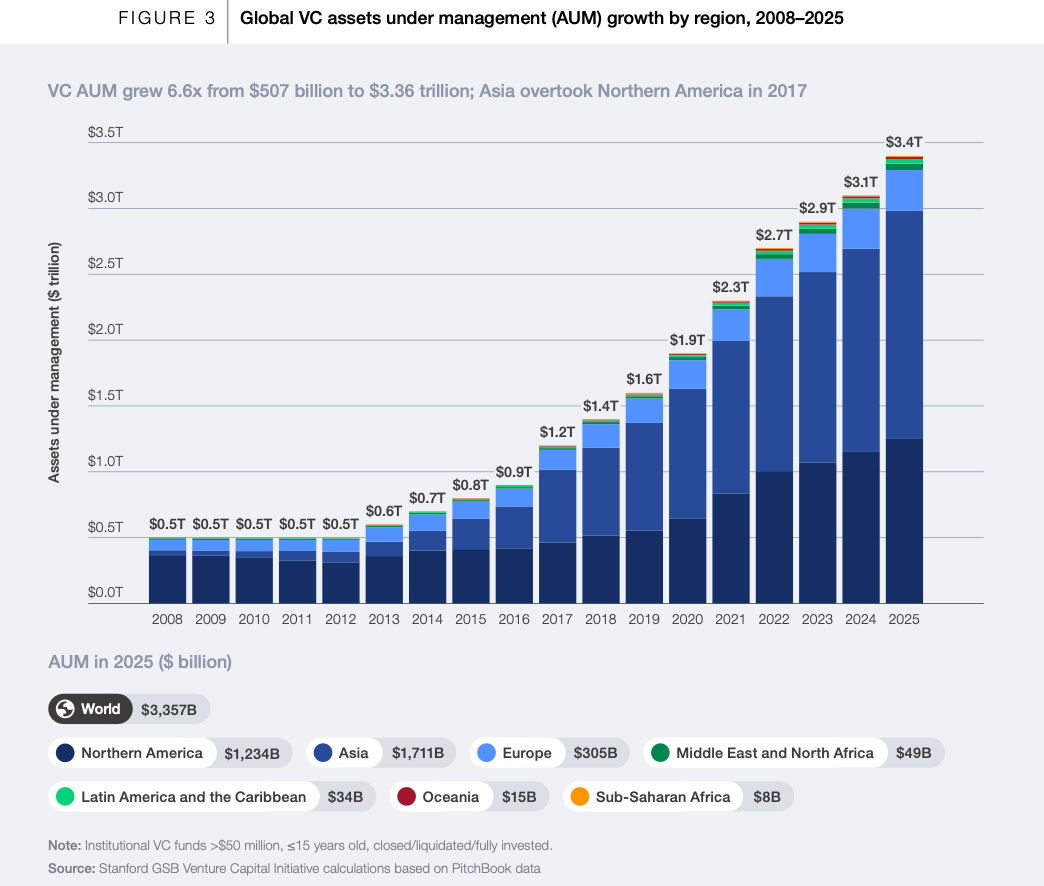
Happy Tuesday! Stanford GSB’s latest Venture Capital Initiative report, Unlocking Liquidity and Growth shows how dramatically venture markets have changed over the past 15 years. Global VC assets under management grew from ~$507B in 2008 to ~$3.36T in 2025, while companies increasingly stay private for 10–15+ years before liquidity. IPO activity remains structurally below prior decades, unrealized venture NAV reached roughly ~$3.2T, and more venture value now sits inside private markets for longer periods. The result is that venture capital increasingly behaves like a longer-duration private-market asset class. More below!
Brought to you by:
Visible - No more chasing founders or wrangling spreadsheets. Finance teams at top VC firms use Visible’s AI-driven platform to streamline portfolio monitoring, stay audit-ready, and impress LPs. Find out why our customers love us today.
AngelList - As VC firms scale their institutional LP base, finance is no longer just back-office hygiene—it’s a strategic advantage. AngelList’s fund admin operates like an outsourced COO, streamlining operations, meeting institutional diligence standards, and delivering timely, accurate reporting. See why 25k funds and syndicates trust AngelList.
Pliancy - Experience the freedom of IT that just works. Partnering with Pliancy means regaining the time & energy to focus on your mission—without having to worry about the day-to-day tech that makes it possible. Discover why VC firms from coast to coast choose Pliancy (or ask about us in VCBC).
Airstream Alpha CFO - Modern CFO support for venture funds and investment firms. With 50+ CFO mandates, Airstream Alpha brings structured, tech-forward oversight and guidance to fund finance, from reporting and compliance to service-provider coordination, so partners stay focused on investing and LP relationships. Learn how funds work with Airstream Alpha from first close through scale.
1️⃣ Venture Capital Has Scaled Dramatically
Recent data showed global VC assets under management increasing from ~$507B in 2008 to ~$3.36T in 2025.
The industry added more than ~$2T of AUM in less than a decade.
The report also noted that Asia overtook North America in VC AUM in 2017, reflecting how venture capital increasingly expanded into a global private-market ecosystem.
What this means:
The venture market now manages a vastly larger pool of private assets than it did a decade ago. Larger capital pools increasingly support companies through extended private growth cycles, larger financing rounds, and delayed liquidity timelines.
2️⃣ VC-Backed Companies Are Staying Private Much Longer
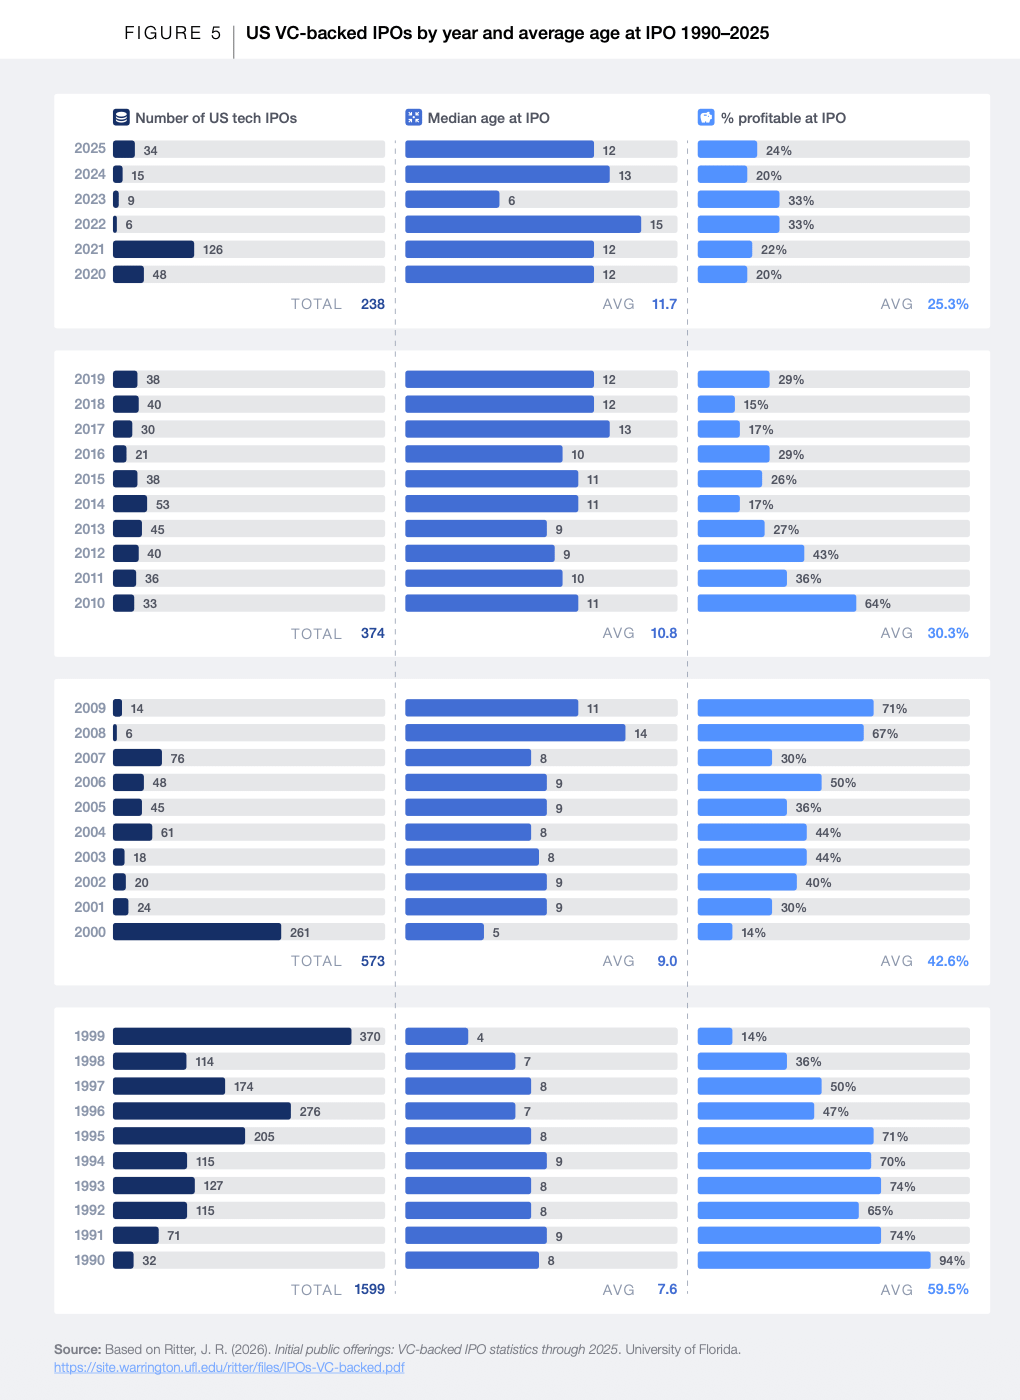
The median age of US VC-backed companies at IPO increased steadily over time:
1990s: ~7.6 years
2000s: ~9.0 years
2010s: ~10.8 years
2020–2025: ~11.7 years
Recent IPO cohorts remained elevated:
2025: ~12 years
2024: ~13 years
2022: ~15 years
IPO volumes also remain structurally below prior decades.
Total US VC-backed IPOs:
1990s: 1,599 IPOs
2000s: 573 IPOs
2010s: 374 IPOs
2020–2025: 238 IPOs
The percentage of profitable VC-backed IPOs also declined materially over time:
1990s: ~59.5%
2020–2025: ~25.3%
What this means:
More value creation increasingly occurs inside private markets rather than public markets. Companies now stay private through additional financing rounds, larger scale phases, and longer operating timelines before reaching liquidity events.
3️⃣ Most Unicorns Are Now More Than 10 Years Old
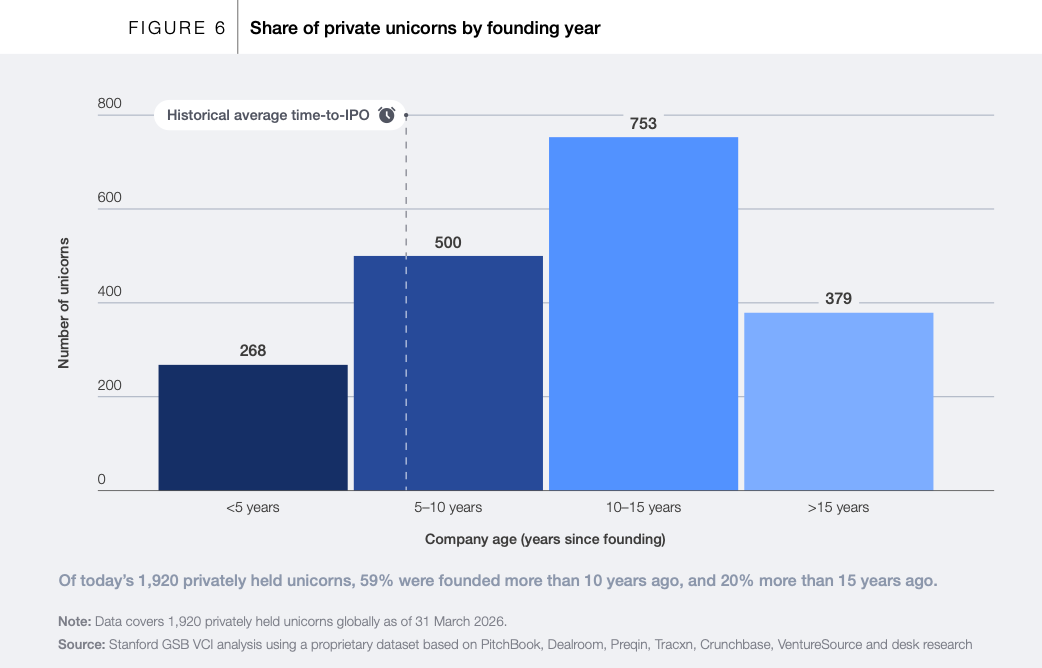
The report identified ~1,920 privately held unicorns globally as of March 2026.
Unicorn age distribution showed:
<5 years: 268
5–10 years: 500
10–15 years: 753
15 years: 379
In total:
~59% of private unicorns were founded more than 10 years ago
~20% were founded more than 15 years ago
The largest group of unicorns now falls into the 10–15 year range.
What this means:
The unicorn category increasingly represents mature private companies rather than newly emerging startups. Many venture-backed businesses now remain private for extended periods while continuing to raise capital and compound value inside private markets.
4️⃣ Unrealized Venture Value Continues Building Inside Private Markets
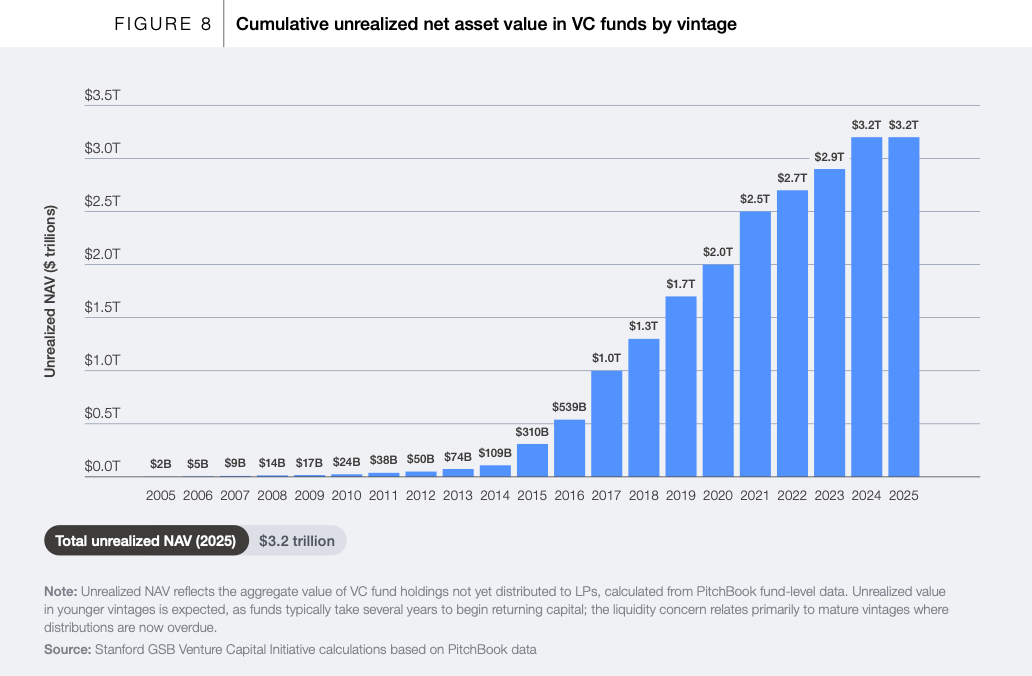
Cumulative unrealized NAV in VC funds increased dramatically over time. The report estimated total unrealized NAV in venture funds at roughly ~$3.2T.
As we discussed in #343: Venture Returns Continue Recovering, valuation recovery has outpaced liquidity recovery across much of the venture market.
What this means:
An enormous amount of venture value now remains unrealized inside private markets. As holding periods extend and IPO activity remains constrained, venture funds increasingly manage larger pools of paper value waiting for future liquidity.
5️⃣ DPI Recovery Remains Slow
Cash distributions across recent venture vintages remain significantly weaker than prior cycles.
At the four-year mark:
2017 vintages:
~46.1% of funds returned only 0–25% DPI
2021 vintages:
~74.8% of funds returned only 0–25% DPI
Additional data showed:
only ~3.3% of 2021 funds exceeded 100% DPI after four years
fewer funds reached higher distribution thresholds relative to prior vintages
liquidity realization continues lagging valuation growth
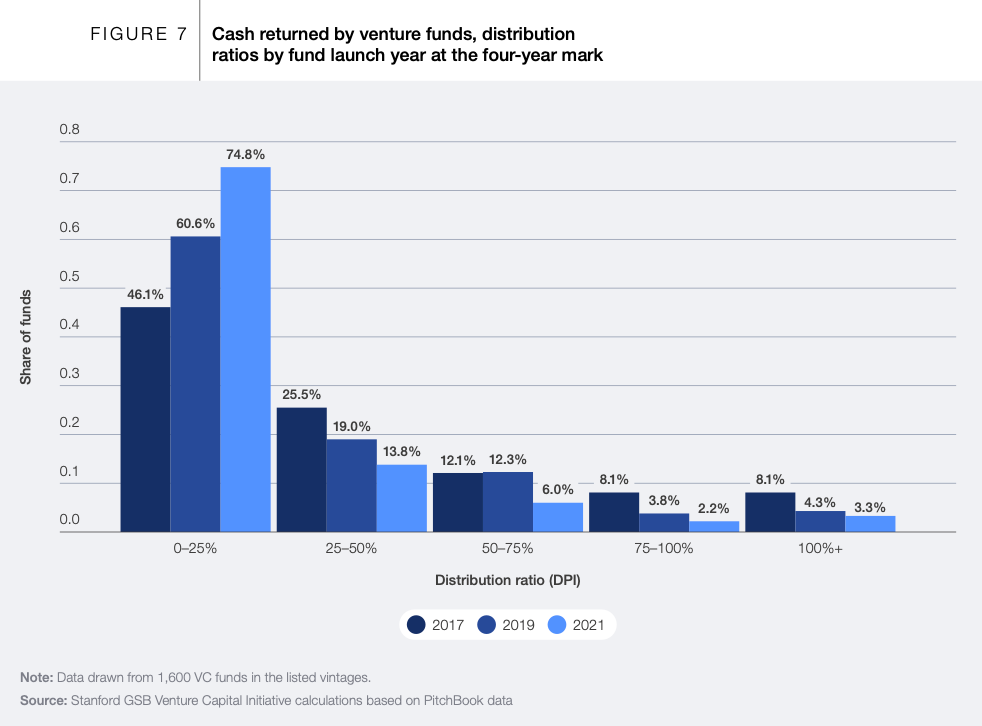
This theme also appeared in #317: TVPI Is Up. DPI Is Not. and in also #343 where improving IRRs continued to outpace realized distributions.
What this means:
Venture performance increasingly depends not just on valuation growth, but on how and when liquidity actually arrives. Larger unrealized portfolios do not automatically translate into realized cash distributions for LPs.
Final Takeaways
global VC AUM grew from ~$507B to ~$3.36T since 2008
companies increasingly stay private for 10–15+ years
IPO activity remains structurally below prior decades
most unicorns are now more than 10 years old
unrealized venture NAV reached roughly ~$3.2T
DPI recovery across recent vintages remains slow
more venture value increasingly remains inside private markets for longer periods
Bottom line:
Venture capital in 2026 increasingly behaves like a longer-duration private-market asset class. As companies stay private longer and unrealized value continues building inside private markets, liquidity timing, reserve planning, and long-duration portfolio management increasingly determine how venture funds ultimately realize returns.
That’s all for today folks! Thanks for your support and spreading the word! Share this on Twitter or LinkedIn to help grow “the crew!”
Every Tuesday/Thursday, we publish VC/CFO insights that matter - highlights from notable VC GPs, LPs, and CFOs/finance pros. Check out our VC Fund Playbooks, Models, Budgets, & Compliance Checklists @ AirstreamAlpha Products!
Need more help? Check out Fund CFO Support provided by the Airstream Alpha Team.
Love what we’re doing? Consider upgrading to paid for deeper dives on Thursdays (most paid subscribers expense these insights!). Top recent posts: