
Happy Thursday! Recent venture headlines continue to focus on AI mega-rounds and record funding totals. But The April 2026 US Venture Capital Funding Report from AlleyWatch, CB Insights, PitchBook, and Carta shows a more nuanced picture underneath the surface. Yes, capital remains heavily concentrated into a small number of companies and AI-related sectors. But outside the mega-rounds, the broader venture market is still active. Venture in 2026 is not broadly booming, but it is no longer broadly frozen either. More below!
Brought to you by:
Visible - No more chasing founders or wrangling spreadsheets. Finance teams at top VC firms use Visible’s AI-driven platform to streamline portfolio monitoring, stay audit-ready, and impress LPs. Find out why our customers love us today.
AngelList - As VC firms scale their institutional LP base, finance is no longer just back-office hygiene—it’s a strategic advantage. AngelList’s fund admin operates like an outsourced COO, streamlining operations, meeting institutional diligence standards, and delivering timely, accurate reporting. See why 25k funds and syndicates trust AngelList.
Pliancy - Experience the freedom of IT that just works. Partnering with Pliancy means regaining the time & energy to focus on your mission—without having to worry about the day-to-day tech that makes it possible. Discover why VC firms from coast to coast choose Pliancy (or ask about us in VCBC).
Airstream Alpha CFO - Modern CFO support for venture funds and investment firms. With 50+ CFO mandates, Airstream Alpha brings structured, tech-forward oversight and guidance to fund finance, from reporting and compliance to service-provider coordination, so partners stay focused on investing and LP relationships. Learn how funds work with Airstream Alpha from first close through scale.
1️⃣ April’s Headline Numbers Look Massive
Recent April 2026 venture data showed:
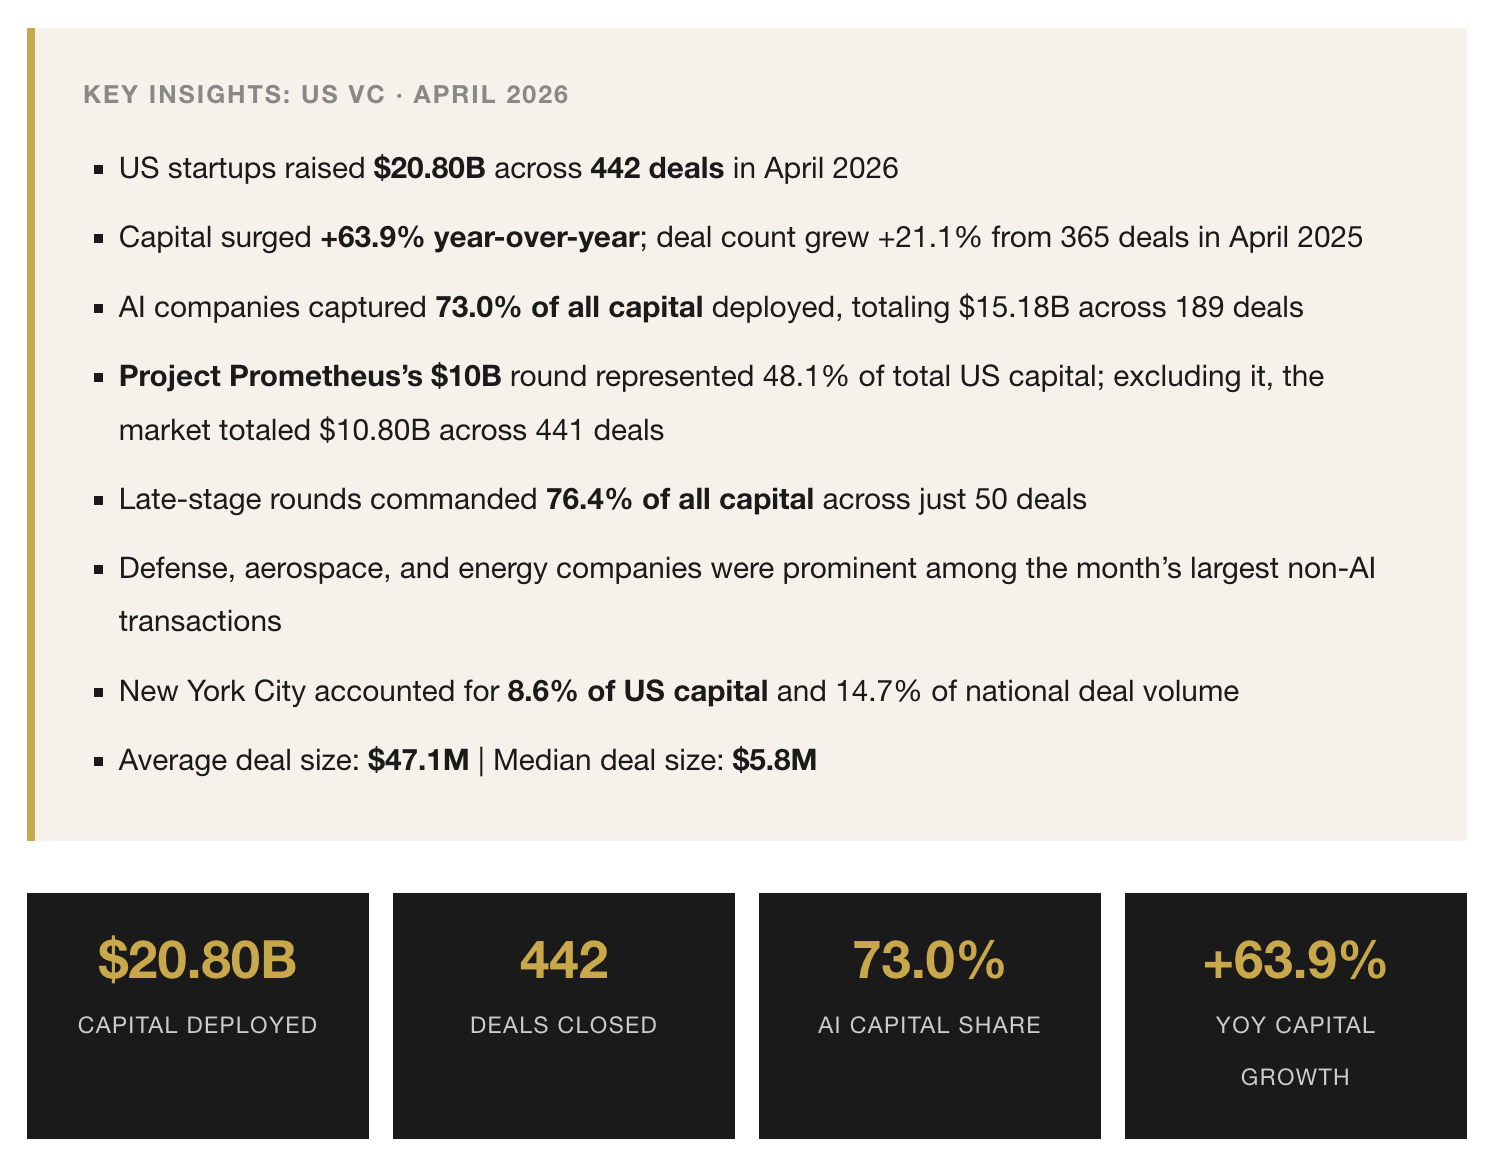
~$20.8B invested across 442 US deals
capital up ~64% YoY
deal count up ~21% YoY
Meanwhile:
AI remained the dominant funding category
several mega-rounds pushed aggregate totals materially higher
late-stage fundraising recovered faster than liquidity and exits
What this means:
At the surface level, venture activity looks strong again. Quarterly funding levels continue recovering, deal counts improved, and large rounds remain active across AI and infrastructure-related sectors. Compared to 2023 and early 2024, the market is clearly more active.
2️⃣ One Deal Drove Nearly Half the Market
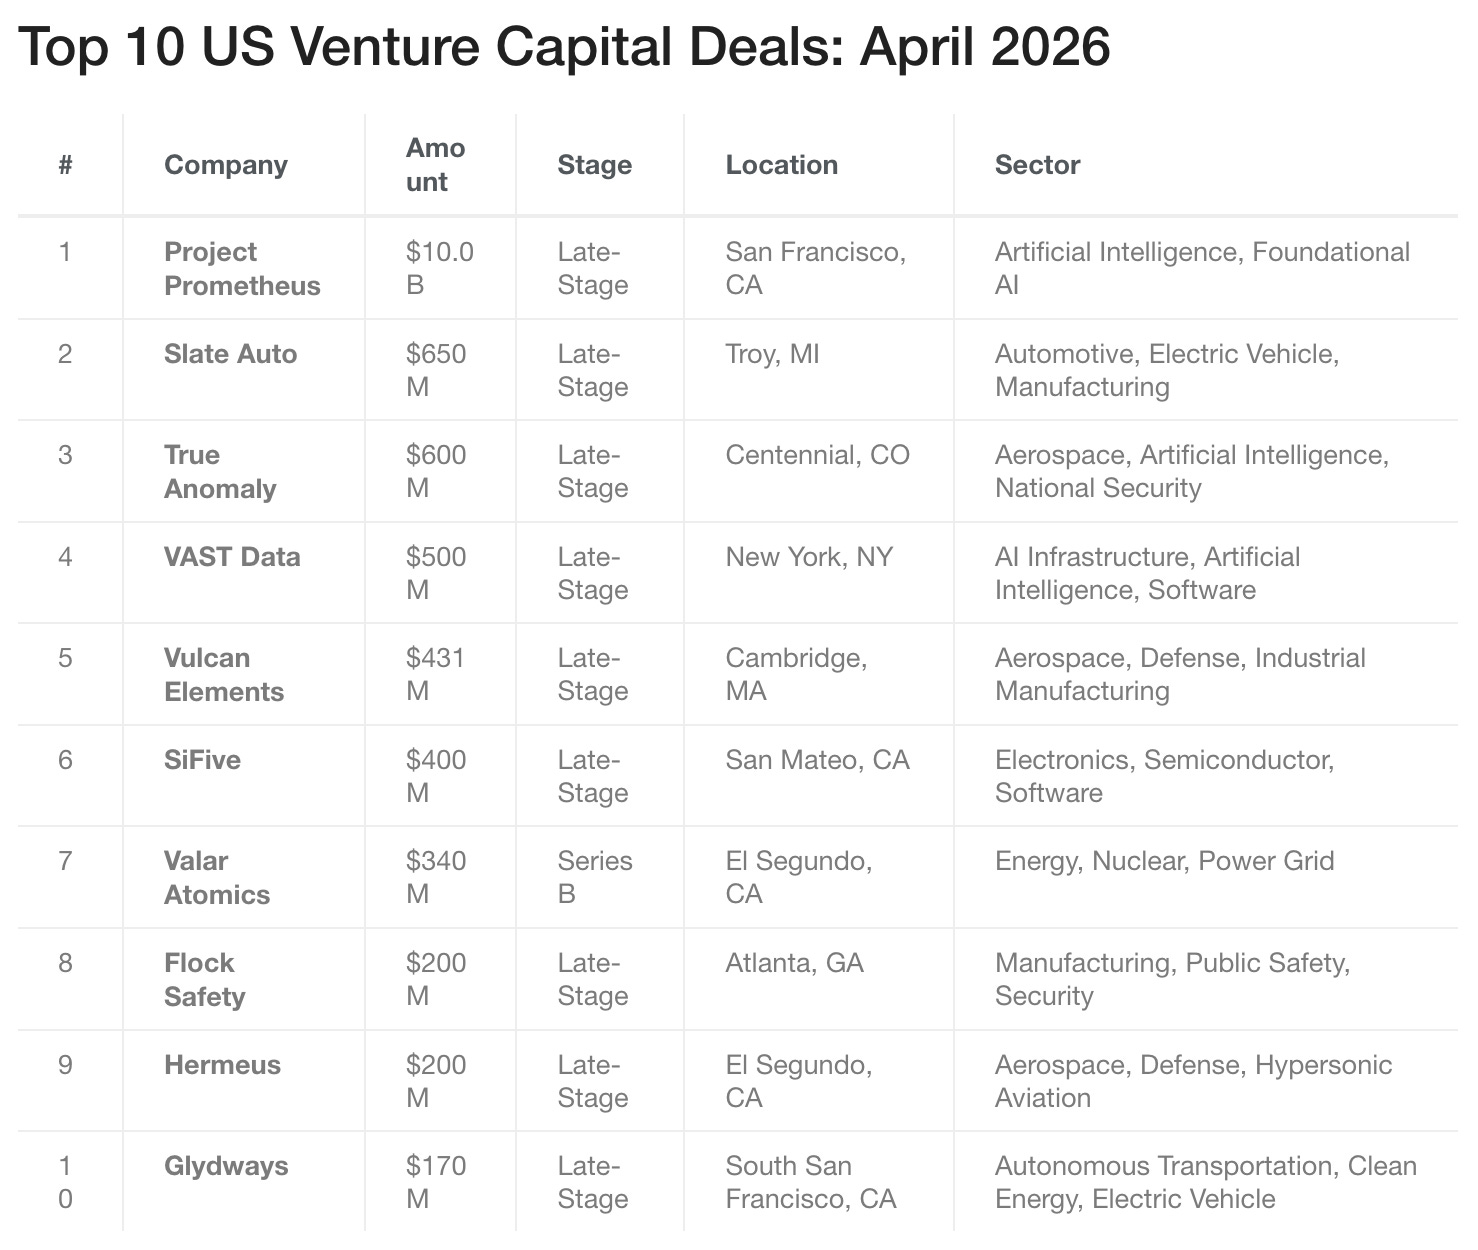
A single financing, Project Prometheus (~$10B), represented nearly half of total April funding volume.
Without that round:
April funding falls from ~$20.8B to ~$10.8B
the market still produced ~441 completed deals
broader activity remained relatively healthy
Meanwhile:
OpenAI-related funding continues heavily influencing aggregate venture statistics
mega-round concentration remains historically elevated
a small number of companies increasingly shape quarterly market narratives
What this means:
The venture market remains highly concentrated at the top end. A handful of AI and infrastructure companies continue absorbing enormous amounts of capital, which can make the broader market appear stronger than it actually is. But removing those mega-rounds does not make the market disappear. Underneath the concentration, there is still meaningful venture activity occurring across the broader ecosystem.
3️⃣ Venture Is No Longer One Market
One side of the market increasingly revolves around AI infrastructure, foundation models, semiconductors, defense, and large-scale compute platforms. These companies continue raising very large rounds at high valuations from concentrated pools of institutional capital.
At the same time, traditional SaaS and broader venture fundraising remain far more selective, with investors increasingly cautious outside top-tier companies.
What this means:
Venture capital in 2026 increasingly behaves like multiple markets operating simultaneously. Capital is flowing aggressively into a narrow set of AI and infrastructure themes, while the broader market remains far more selective. “VC is back” depends heavily on which part of the market you are looking at.
4️⃣ The Underlying Market Is More Durable Than Headlines Suggest
Even excluding mega-rounds:
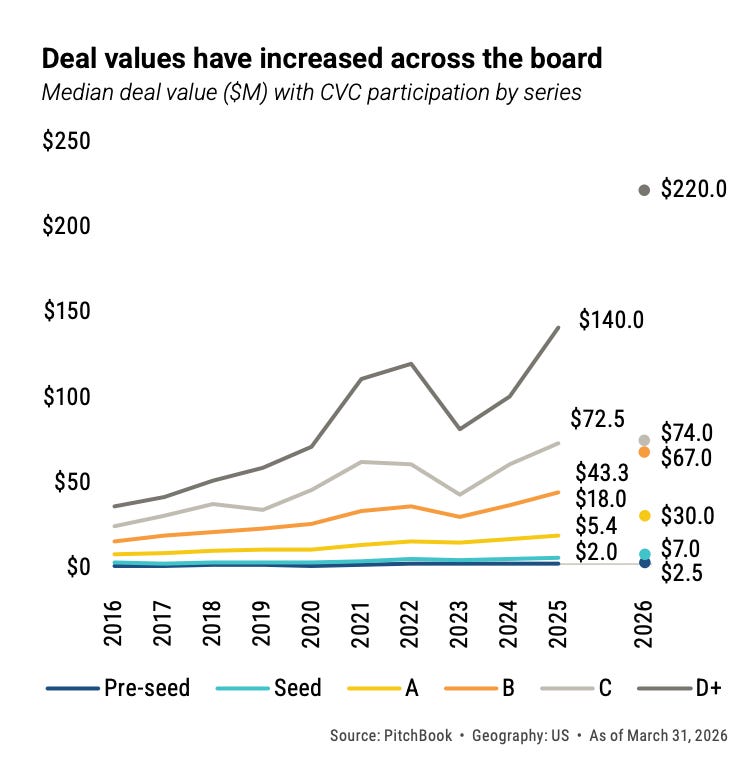
hundreds of companies still raised capital in April
deal activity improved year-over-year
seed and Series A activity continued
secondaries and continuation vehicles continued expanding liquidity options
Meanwhile:
companies increasingly stay private longer
venture firms continue supporting existing portfolios
private liquidity solutions increasingly supplement traditional IPO exits
What this means:
The market may not be broadly euphoric, but it is functioning. Companies are still raising, investors are still deploying, and liquidity mechanisms continue evolving inside private markets. The current environment looks less like a frozen market and more like a highly selective one.
5️⃣ What This Means for Venture Funds
Recent trends increasingly reward firms that can:
access competitive AI and infrastructure deals
maintain reserves across longer holding periods
navigate concentrated markets
continue funding companies across longer private holding periods
At the same time:
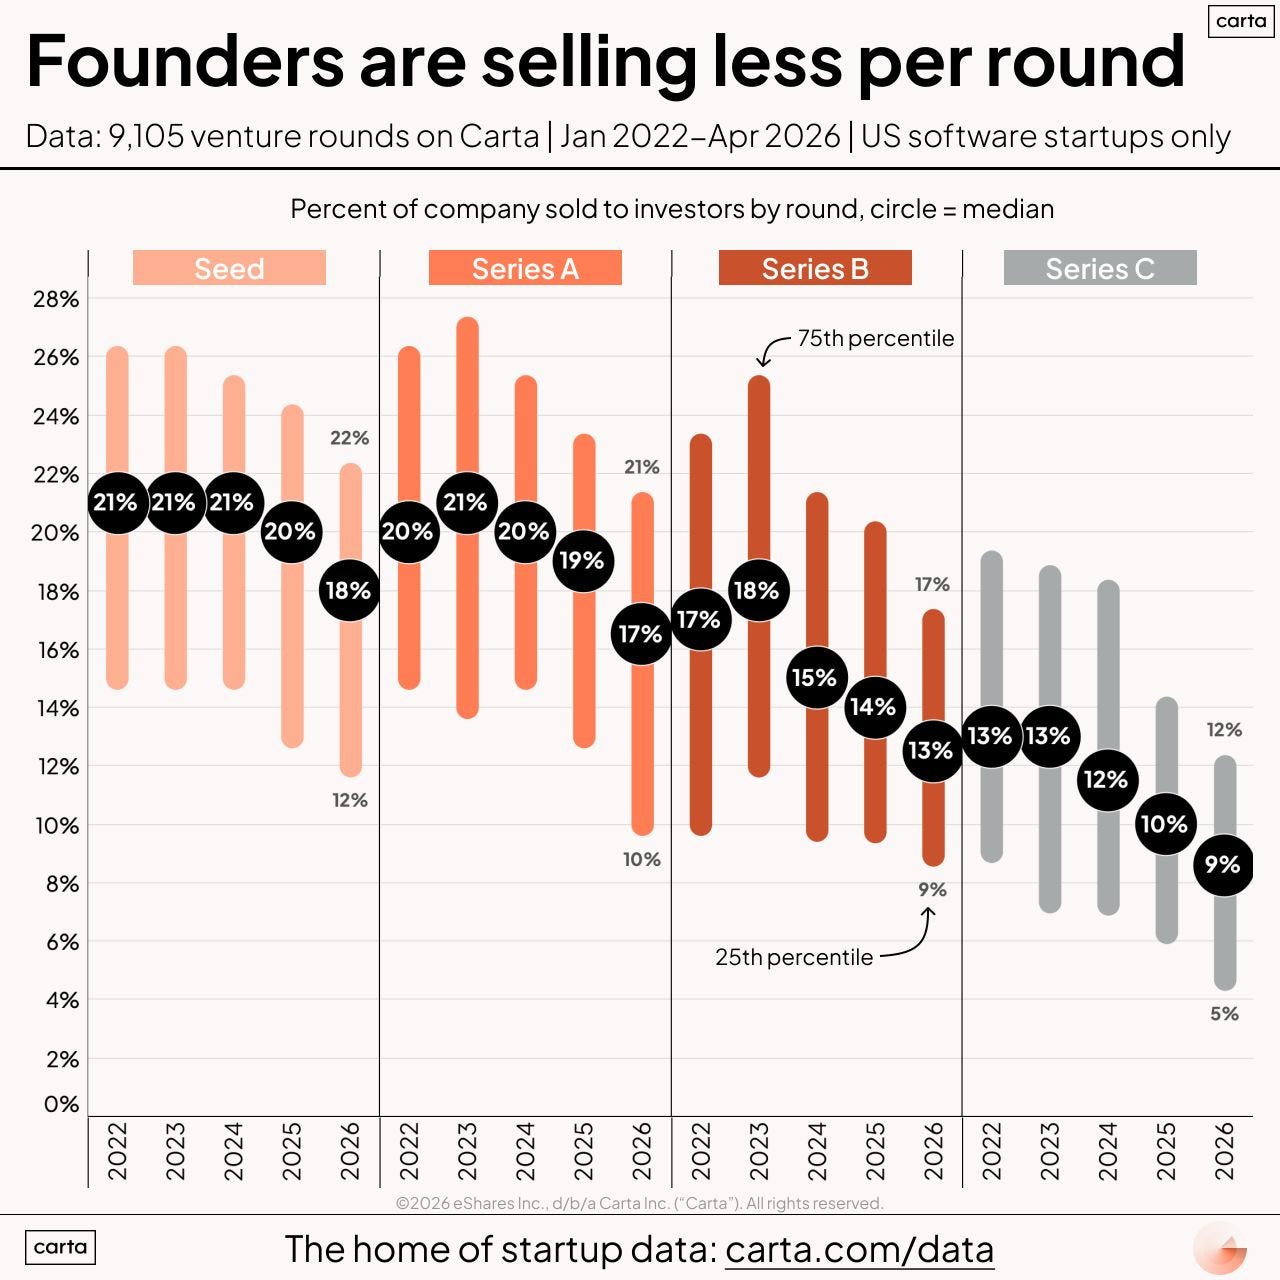
ownership is becoming harder to maintain (#340)
larger rounds increasingly compress ownership percentages
What this means:
Fund performance increasingly depends on selectivity, ownership retention, and long-duration portfolio management. The challenge for venture firms is no longer simply deploying capital. It is maintaining meaningful exposure in the companies that continue compounding value inside private markets.
Final Takeaways
April 2026 venture funding reached ~$20.8B
one ~$10B round represented nearly half the market
excluding mega-rounds, underlying venture activity still remained active
AI and infrastructure continue dominating capital flows
venture increasingly operates like multiple markets at once
the broader venture ecosystem remains selective, but functional
Bottom line: Venture capital in 2026 is highly concentrated, but not broadly dead. Mega-rounds may dominate headlines, but underneath them, the broader market continues adapting, deploying, and evolving.
Subscriber Toolkit: Fund Models in Selective Markets
Reserves determine ownership, dilution, and how much of an outcome a fund actually captures.
Paid subscribers can access:
VC Fund Model Template
Model reserve allocation, ownership retention, and fund-level outcomes
DPI Forecast & Capital Call Template
Incorporate longer holding periods and staged liquidity
Waterfall Distribution Model
Understand how ownership concentration impacts distributions
Quarterly Financial Review Template
Track capital deployment, reserves usage, and portfolio concentration
That’s all for today folks! Thanks for your support and spreading the word! Share this on Twitter or LinkedIn to help grow “the crew!”
