

Happy Tuesday! Today, we unpack Erik Torenberg’s “The Case for Scaling Venture”, which argues that venture firm scale reflects structural changes in company outcomes and capital needs. This contrasts somewhat with takes from Roelof Botha (Sequoia) on Uncapped (Jack Altman). “Go big or go boutique” - is that the future of venture capital? We dive deeper into the data to find out.
Brought to you by:
Visible - No more chasing founders or wrangling spreadsheets. Finance teams at top VC firms use Visible’s AI-driven platform to streamline portfolio monitoring, stay audit-ready, and impress LPs. Find out why our customers love us today.
AngelList - As VC firms scale their institutional LP base, finance is no longer just back-office hygiene—it’s a strategic advantage. AngelList’s fund admin operates like an outsourced COO, streamlining operations, meeting institutional diligence standards, and delivering timely, accurate reporting. See why 25k funds and syndicates trust AngelList.
Pliancy - Experience the freedom of IT that just works. Partnering with Pliancy means regaining the time & energy to focus on your mission—without having to worry about the day-to-day tech that makes it possible. Discover why VC firms from coast to coast choose Pliancy (or ask about us in VCBC).
Zooming Out to 5 Year Windows: VC Exit Value Growth
One way to evaluate whether venture is actually “scaling” is to look at exit size over time. This chart looks at the 90th and 99th percentile exit values in five-year windows. That helps isolate how the upper end of the outcome distribution has changed across cycles.
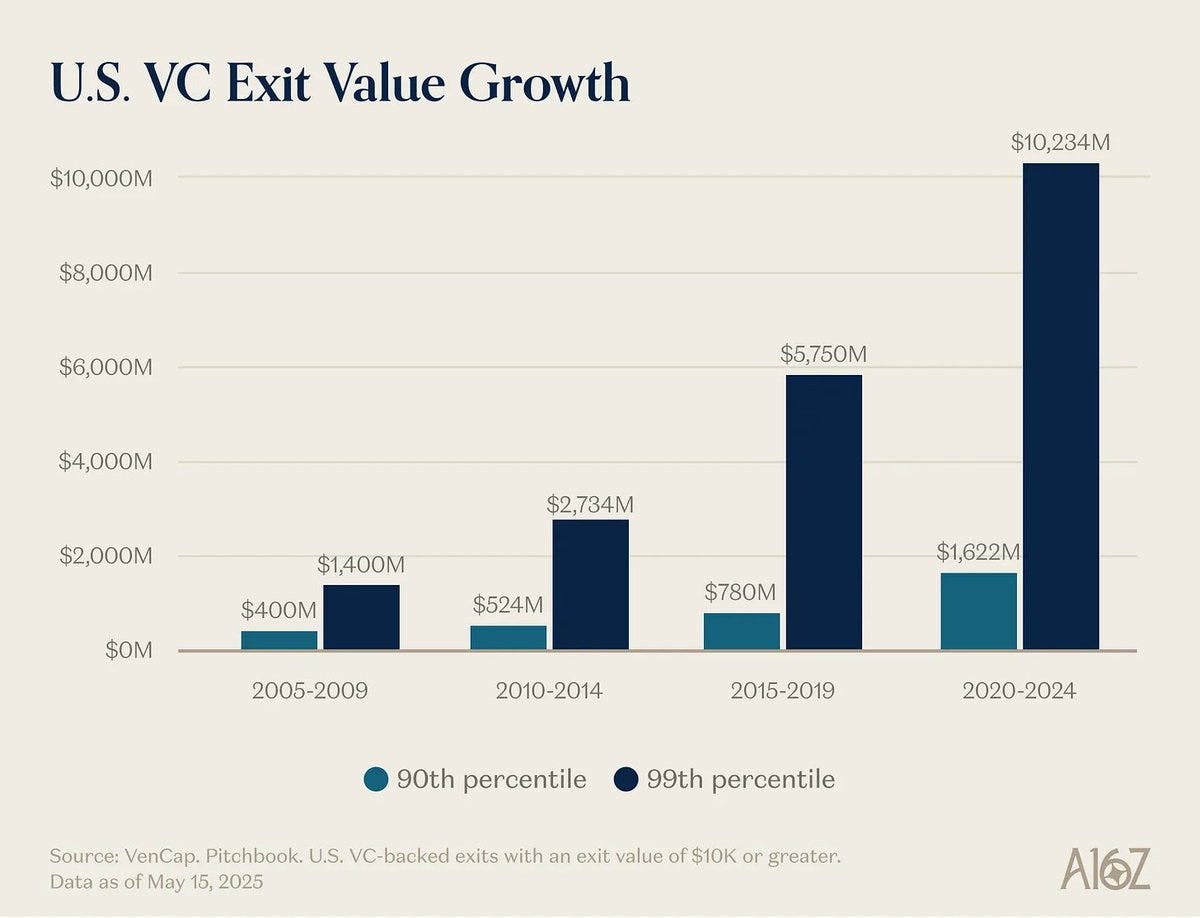
90th percentile exit values increased from ~$400M (2005–2009) to ~$1.6B (2020–2024)
99th percentile exit values increased from ~$1.4B to ~$10.2B over the same period
The upper tail of venture outcomes has expanded materially over two decades
What this means:
Top-end exits are larger than in prior cycles. The scaling argument relies partly on this expansion. If the 99th percentile is now above $10B, larger funds can be evaluated against a higher ceiling for potential outcomes.
Revenue Scale and Company Size Have Increased
Annual companies reaching $100M in revenue increased from roughly ~15 historically to close to an order of magnitude more today, per the article
Venture-backed companies now represent a meaningful share of total public market value
The perceived ceiling for startup outcomes has shifted from billion-dollar exits to $100B+ and potentially trillion-dollar companies
What this means:
The claim that the number of winners is fixed is challenged by pointing to more companies reaching material revenue scale and larger potential outcomes. The argument assumes that revenue growth and market cap expansion reflect a larger opportunity set for venture.
Capital Intensity Has Increased, Especially in AI and Infrastructure
Frontier AI companies are spending billions on GPUs and compute infrastructure
Companies such as OpenAI, Anthropic, xAI, Anduril, and Waymo raised large early rounds
Modern technology companies frequently require hundreds of millions in capital before IPO
More companies are vertically integrating into infrastructure and hardware
What this means:
Per-company capital requirements have increased, particularly in AI and infrastructure-heavy sectors. If companies require more capital and stay private longer, larger venture funds can be viewed as a response to increased financing requirements.
Deal Competition and Allocation Dynamics Have Changed
There has been a significant increase in the number of venture firms
Founders can access multiple term sheets more easily than in prior decades
Companies remain private longer, allowing later-stage entry while targeting venture-scale outcomes
More repeat founders and faster scaling companies reduce informational asymmetry
What this means:
Winning allocation is positioned as increasingly important. If top companies are widely known and competitive, access and ability to support founders become differentiators. Scale is presented as one way to compete in that environment.
Roelof Botha’s (Sequoia) VC Claims and Counterpoints
In a recent release of Uncapped (Jack Altman), Roelof Botha shared insights on his views regarding winner concentration, capital supply, and industry size in VC. Erik Torrenberg pushes back on some of the claims, making his case for a16z:
Fixed number of winners
Counterpoint presented: more $100M revenue companies and materially larger exit ceilings.Too much capital chasing too few companies
Counterpoint presented: longer private duration and higher capital intensity increase per-company capital requirements.The industry should be smaller
Counterpoint presented: startup market cap and large outcomes have expanded alongside venture capital growth.
These rebuttals rely primarily on exit distribution data, revenue growth milestones, and capital intensity trends.
Our Takeaways
Big exits are much bigger than before. $10B+ outcomes now appear in the 99th percentile range, not just as outliers. That makes larger funds possible, but only if you actually invest in those companies.
The case for large funds makes the most sense in AI and other capital-heavy sectors. Those companies genuinely need billions. That logic does not apply equally to every sector.
Companies are staying private longer. If you do not have reserves to keep investing, your ownership will shrink before exit.
Bigger funds mean you rely more on a few very large winners. Even if exits are bigger, returns are still driven by a small number of companies.
Larger opportunities do not remove LP constraints. Liquidity timing and allocation pacing still matter, regardless of how big companies become.
Scaling depends on consistent access to the top end of the exit distribution and the ability to maintain ownership through extended private cycles.
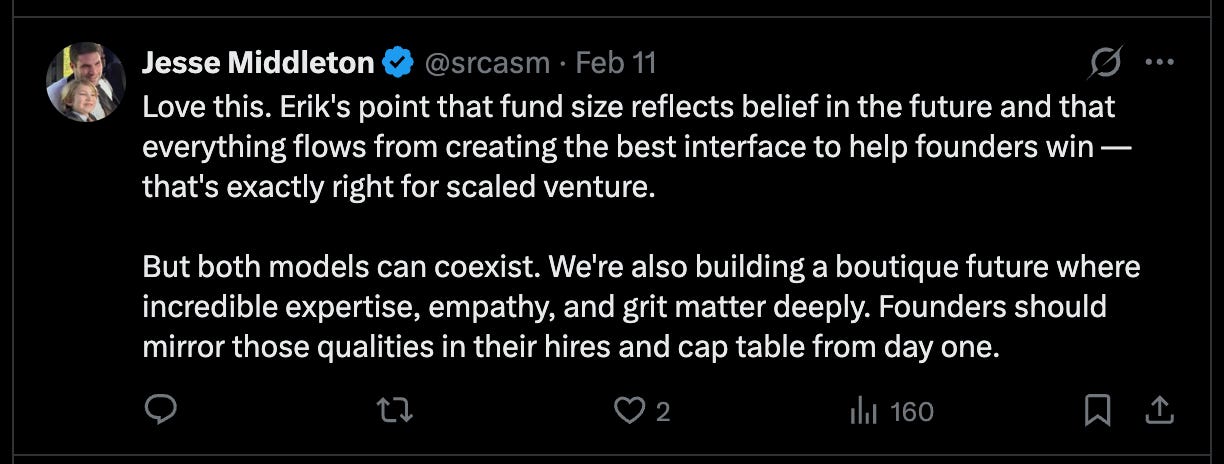
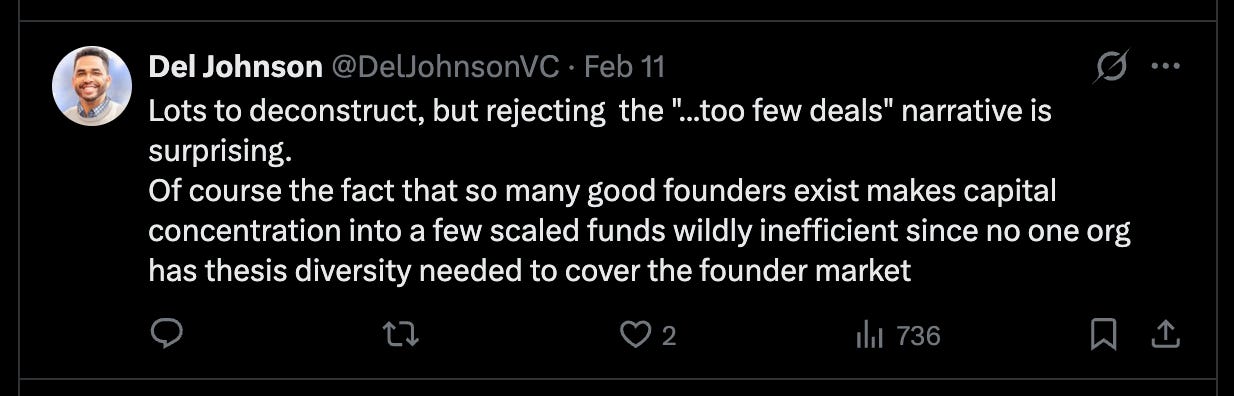
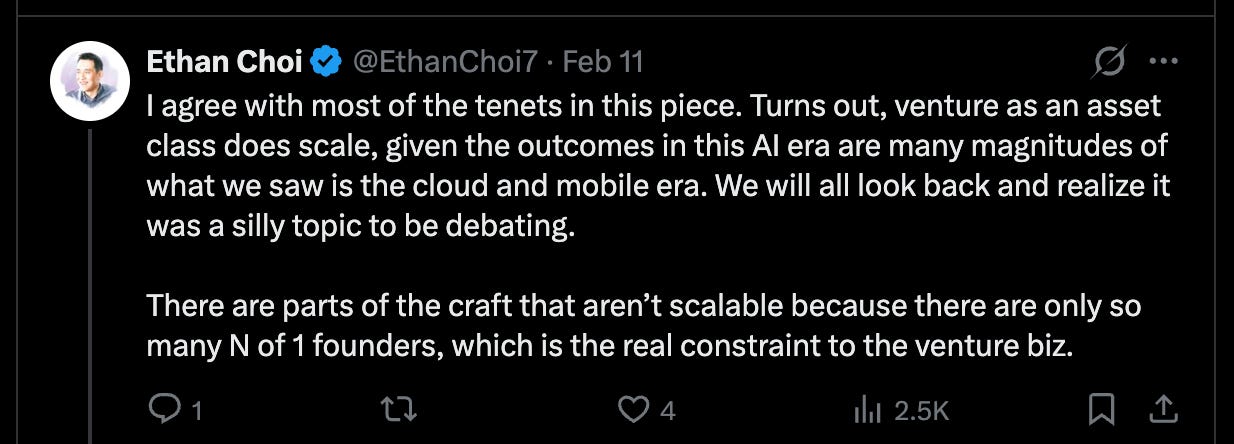
Additional Reactions on X
That’s all for today folks! Thanks for your support and spreading the word! Share this on Twitter or LinkedIn to help grow “the crew!”
Every Tuesday/Thursday, we publish VC/CFO insights that matter - highlights from notable VC GPs, LPs, and CFOs/finance pros. Check out our VC Fund Playbooks, Models, Budgets, & Compliance Checklists @ AirstreamAlpha Products!
Need more help? Check out Fund CFO Support provided by the Airstream Alpha Team.
Love what we’re doing? Consider upgrading to paid for deeper dives on Thursdays (most paid subscribers expense these insights!). Top recent posts:
Hi Doug! I think venture will divide into two tiers with Big funds and Boutique funds. Big funds will focus on companies that have the potential to exit at the least with a $1B valuation. The funds in the middle will get wiped out. Boutique fund will mainly focus on delivering sector-specific expertise and agility with respect to deal closing.
I write on VC and Startups in the LegalTech focused on analyzing investment opportunities and identifying whitespaces to build. I've written a short post on analyzing three such whitespaces for 2026. Would love to get your thoughts on it as an investor!
https://harshithviswanath.substack.com/p/three-legaltech-whitespace-plays